The evolution of competitive gaming—commonly known as esports—has transitioned from a niche subculture into a mainstream global phenomenon. What began as small, LAN-based tournaments in the late 1990s has matured into a multi-billion-dollar industry with professional leagues, corporate sponsorships, and a fan base that rivals traditional sports. This article examines the key drivers behind this explosive growth, the economic forces at play, and the structural changes that have solidified esports as a permanent fixture in the global entertainment landscape.
From Basements to Arenas: A Historical Context
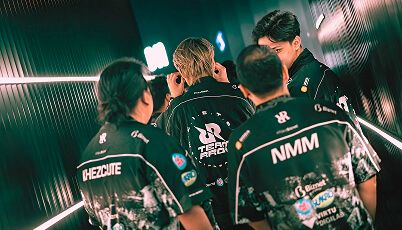
The roots of competitive gaming can be traced to the arcade era, where high-score competitions created the first rudimentary rivalries. However, the true catalyst was the advent of online multiplayer and broadband internet in the early 2000s. Titles like StarCraft in South Korea and Counter-Strike in Europe established the template for modern esports: dedicated teams, training regimens, and live audiences. By 2010, streaming platforms such as Twitch removed geographic barriers, allowing anyone with a connection to watch top-tier play in real time. This accessibility transformed passive viewership into a global interactive experience, laying the groundwork for the industry’s current scale.
Economic Expansion and Market Valuations
The financial trajectory of esports is staggering. Industry reports estimate the global esports market will exceed $1.8 billion in revenue by 2025, growing at a compound annual rate of over 20%. This growth is not monolithic; it is driven by a diversified revenue stream that includes media rights, sponsorship deals, merchandise sales, and digital advertising. Unlike traditional sports, esports benefits from a digitally native audience that is highly engaged across multiple platforms, making it exceptionally attractive to tech companies and venture capitalists.
Key Revenue Segments: A Comparative View
| Sponsorship & Advertising | $640M | $1.1B | Brand partnerships with non-endemic companies |
| Media Rights & Broadcasting | $280M | $420M | Exclusive streaming deals and OTT platforms |
| Merchandise & Tickets | $110M | $180M | Live arena events and team apparel |
| Game Publisher Fees | $90M | $150M | Licensing of competitive circuits |
This financial robustness has attracted institutional investors. Franchise slots in major leagues such as the League of Legends Championship Series (LCS) or the Overwatch League have sold for sums exceeding $10 million, with traditional sports team owners—including members of NBA and NFL franchises—purchasing stakes. The convergence of sports capital and tech infrastructure signals strong confidence in long-term sustainability.
Regional Dominance and Emerging Markets
While esports is a global phenomenon, its growth is uneven. Asia, particularly China and South Korea, remains the undisputed epicenter, accounting for over 50% of global esports revenue. China’s government has actively supported esports as a legitimate career path, even adding it to official sports classifications. South Korea’s cultural integration, with dedicated TV channels and celebrity players, sets a benchmark for acceptance. Conversely, North America and Europe show robust growth but face fragmented tournament structures and higher regulatory hurdles.
Emerging markets are rapidly closing the gap. Countries in Southeast Asia, Latin America, and the Middle East are seeing exponential mobile-first esports adoption. Mobile esports, particularly titles like PUBG Mobile and Free Fire, bypass the need for expensive gaming PCs, enabling mass participation in regions with limited infrastructure. This mobile movement has democratized access, creating a new generation of players in India, Brazil, and Indonesia. The result is a delocalized competitive ecosystem where regional champions can compete on a global stage without historical biases.
Technological Catalysts: Streaming, 5G, and AI
The growth of competitive gaming is inseparable from technological advancement. High-speed 5G networks have reduced latency to imperceptible levels, making remote competition seamless across continents. Cloud gaming platforms such as NVIDIA GeForce Now and Xbox Cloud Gaming allow high-fidelity titles to run on low-end devices, removing hardware barriers. Furthermore, artificial intelligence now powers matchmaking algorithms, anti-cheat systems, and even automated broadcast production, lowering the operational costs of launching new leagues.
- Spectator Experience: Multi-angle replay systems and real-time statistics enhance narrative depth for viewers.
- Virtual Arenas: Persistent digital venues allow concurrent events with zero physical footprint.
- Betting & Fantasy Esports: Legally regulated wagering platforms are new revenue engines and engagement tools.
These technologies do more than improve efficiency; they create new forms of engagement. The rise of “watch-to-earn” models, where viewers receive in-game rewards, is blurring the line between watching and playing, further solidifying the social ecosystem.
Institutionalization and Mainstream Acceptance
As the industry matures, it is adopting the governance models of traditional sports. Player unions, standardized contracts, and anti-doping policies are becoming baseline requirements. Universities now offer esports scholarships, and high schools run official varsity leagues. This institutionalization is critical for parental and corporate acceptance, moving esports away from a “hobby” stigma toward a legitimate professional vocation.
The inclusion of esports in major multi-sport events, such as the Asian Games as a medal event in 2022, is a significant milestone. While Olympic integration remains debated, the mere discussion validates esports as a serious athletic pursuit. The narrative has shifted from “are games sports?” to “how can we optimize competitive performance, monetization, and viewership?”
Challenges and the Path Forward
Despite its momentum, competitive gaming faces existential challenges. Player burnout is rampant due to grueling schedules, and the average career span for a professional player is often under five years. The industry also struggles with oversaturation—too many tournaments and games competing for finite attention spans. Moreover, the reliance on game publishers, who own the intellectual property of the games, creates a structural fragility; a publisher can alter a game’s balance or withdraw a license, destroying an entire league overnight.
Looking ahead, the next phase of growth will be defined by consolidation. Expect larger, more unified circuits with franchised teams that have secure revenue sharing, similar to the English Premier League model. Furthermore, the integration of virtual reality (VR) and augmented reality (AR) may create entirely new competitive dimensions, moving from screen to immersive physical movement. In conclusion, the growth of competitive gaming is not a passing trend but a structural shift in how humanity plays, watches, and values digital competition. Its trajectory is upward, resilient, and continuously redefining the intersection of technology and sportsmanship.

Related Posts